Stablecoin card spending crosses $1 billion in a month as payment use moves beyond crypto trading
Paymentscan data cited by Reuters put July stablecoin-card spending above $1 billion, while RedotPay says cumulative industry spend has passed $10.9 billion.
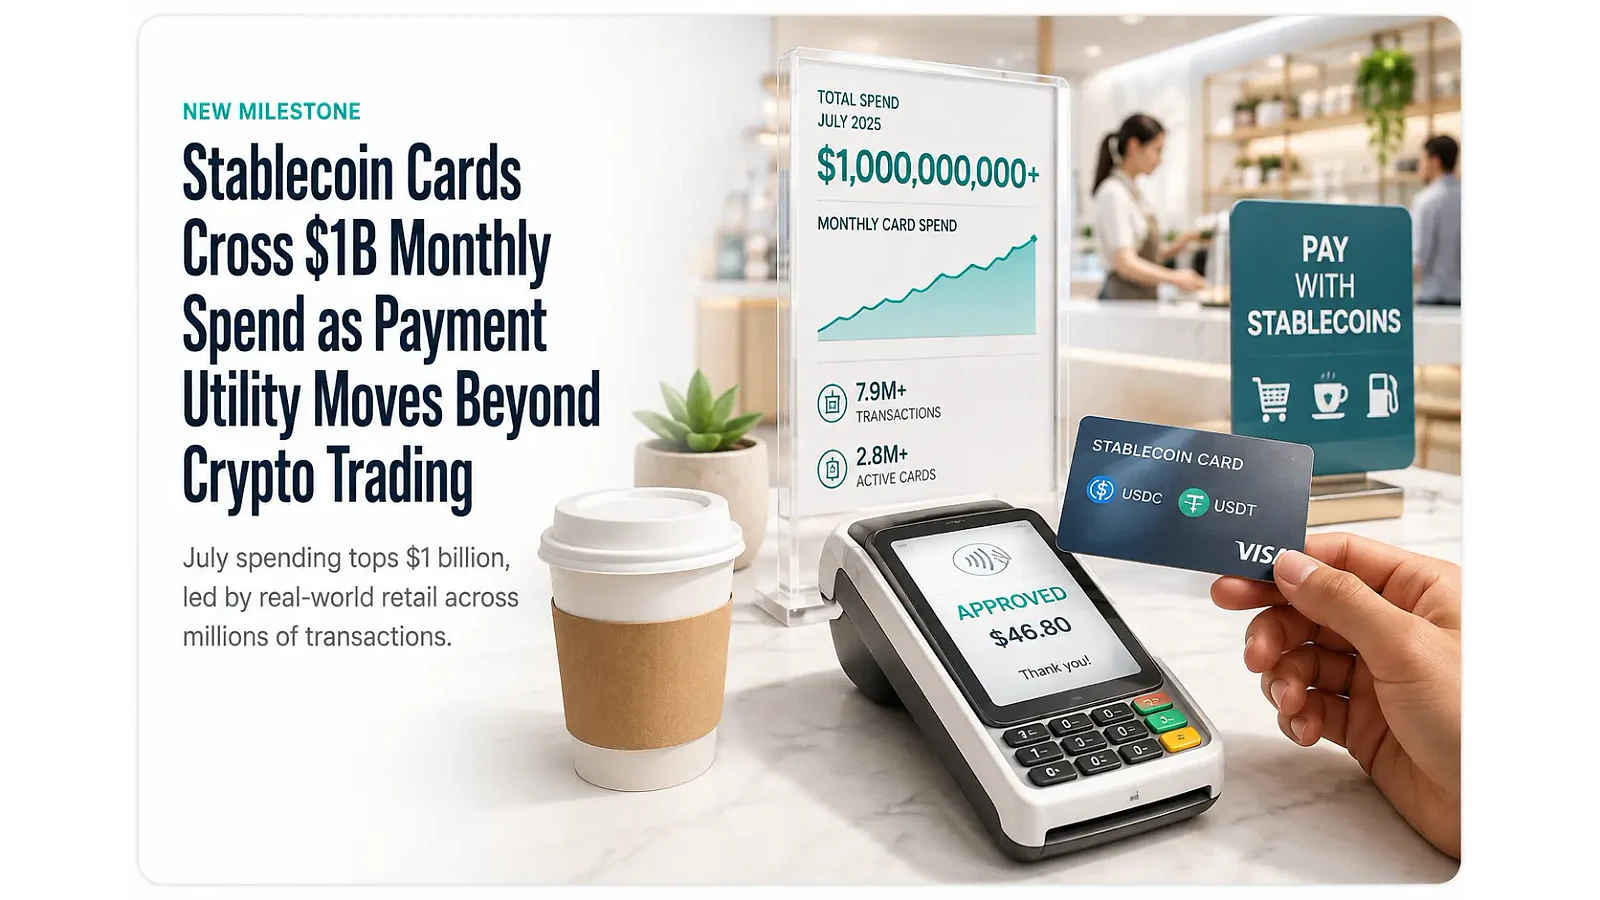
Stablecoin-funded card spending exceeded $1 billion in July 2026, according to Paymentscan data reported by Reuters on August 25, giving the stablecoin market one of its clearest measures yet of executed consumer payment activity rather than token issuance or exchange trading.
The milestone matters because the card is not replacing the merchant acceptance network. In most stablecoin-card models, users fund an account or card balance with digital dollars while conversion and settlement infrastructure connects that balance to existing card rails. The merchant still receives a familiar card payment. What changes is the source of funds upstream.
RedotPay, a Hong Kong-based stablecoin payments company, separately said cumulative spending through stablecoin-powered cards across the industry has exceeded $10.9 billion, citing Paymentscan. The company described July as the industry's highest-volume month to date. Reuters also reported that RedotPay expects annual stablecoin-card spending to reach $50 billion by 2028, but that figure is a company forecast rather than observed market data.
The useful number is spending, not token supply
Stablecoin growth is often described using circulating supply, transfer volume or exchange liquidity. Those measures can be large without demonstrating that a stablecoin is being used to buy goods and services. Card expenditure is narrower, but more directly tied to payment behaviour.
That makes the July figure useful for payments companies. It measures value that reached a card acceptance endpoint, even if the stablecoin itself did not settle directly to the merchant. The model increasingly resembles a layered payment stack: stablecoin balance at the funding edge, conversion and compliance in the middle, and Visa or Mastercard acceptance at the merchant edge.
RedotPay says that when it launched its card three years ago, the industry processed roughly $60,000 per month. Its August 25 publication says stablecoin cards now process that amount in about four minutes. That historical comparison comes from the company and should be treated as a company-supplied market narrative, but the direction is consistent with the Paymentscan record cited by Reuters.
Latin America and Africa are emerging as distribution markets
Reuters quoted RedotPay co-founder and head of partnerships Jonathan Chan saying, “Latin America has the highest adoption and greatest potential for growth at the moment, followed by Africa.”
That geography is commercially significant. Stablecoin cards are most useful where users already hold digital dollars for savings, remittances, freelance income or cross-border commerce but still need access to conventional merchant acceptance. A card can turn a stablecoin balance into spendable value without requiring the merchant to accept a stablecoin directly.
RedotPay told Reuters it serves more than 8 million users and has annualised payment volume above $14 billion. That figure includes account top-ups as well as card expenditure, so it should not be read as $14 billion of annualised purchases. Registered users also do not indicate how many people actively use a card each month.
Stablecoins are becoming an intermediate payment layer
The stronger conclusion from the data is not that stablecoin cards are displacing the card networks. They currently depend on those networks for broad merchant reach. The change is that stablecoins are becoming a funding asset behind conventional payment interfaces.
That distinction is likely to shape competition. Stablecoin issuers can compete for balances and liquidity, fintechs can compete on conversion, compliance and card economics, while card networks preserve distribution at the merchant endpoint. The customer may experience the product as an ordinary payment card even when the funding asset is on-chain.
The $50 billion annual forecast for 2028 should remain clearly attributed to RedotPay. Paymentscan's July record is the more important evidence today: stablecoin cards have moved beyond a hypothetical use case and into measurable consumer spending at billion-dollar monthly scale.
Actual spending and forecasts need to stay separate
Measure — Figure — What it represents
July 2026 stablecoin-card spending — >$1B — Observed industry spending reported from Paymentscan data
Cumulative stablecoin-card spending — >$10.9B — RedotPay figure citing Paymentscan
RedotPay annualised payment volume — >$14B — Company run rate including top-ups and card expenditure
2028 stablecoin-card forecast — $50B/year — RedotPay projection, not observed market volume
Keeping those measures separate is essential. Transfer volume can count movements between wallets; top-ups move value into a payment account; card expenditure records value actually spent through a card. The July milestone is useful precisely because it is the narrowest of those categories. It offers a cleaner signal of consumer payment activity than aggregate blockchain transfer figures that can be inflated by trading, treasury movements or repeated settlement flows.
The $50 billion forecast would imply average monthly spending of roughly $4.2 billion if evenly distributed across a year. That arithmetic illustrates the growth implied by RedotPay's projection, but it is not a separate market forecast and should not be presented as one.